Chicago Board Options Exchange will launch trading in a new type of S&P 500 Index options contract, known as CBOE S&P 500 Range options (SRO), beginning on 28 August.
CBOE Range options were designed to provide individual investors with a lower-risk, lower-cost way to trade S&P 500 Index options.
SROs pay an exercise settlement amount if the settlement value of the underlying index at expiration selected by the investor falls within a specified "range length." The range length for SROs will be set at 70 S&P 500 Index points.
SRO payouts work as follows: if the S&P 500 Index settlement value falls within the middle 50 points of the 70-point range, the payout for the option will be USD1,000. If the S&P 500 Index settlement value falls within the 10 points on either side of the 50-point range, the payout amount will decrease linearly (e.g. positive payout will be between USD999 and USD1) to zero.
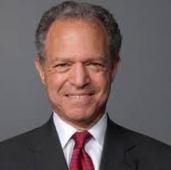
"Range options give investors with an outlook on S&P 500 Index prices a new way to gain exposure to the market - with less need for price precision," says CBOE chairman and chief executive William J Brodsky (pictured). "The new contract brings another dimension to our extensive S&P 500 Index option complex. Like SPX, SPX Weeklys and SPXpm, Range options provide a unique way for our customers to trade the S&P 500. Each of these products underscores CBOE's commitment to develop new and innovative products that address the diverse needs of investors."
Yen carry trade risks mount
Hedge funds and other leveraged investors face renewed risks from the yen carry trade as Japan moves further away from decades of…
More
Valour launches first crypto hedge fund using Neuronomics AI strategy
Valour, the digital asset investment products subsidiary of DeFi Technologies, has launched its first hedge fund as it expands beyond…
More
SocGen targets strong prime brokerage growth
Societe Generale is planning to significantly expand its prime brokerage business as part of Chief Executive Officer Slawomir Krupa's…
More